

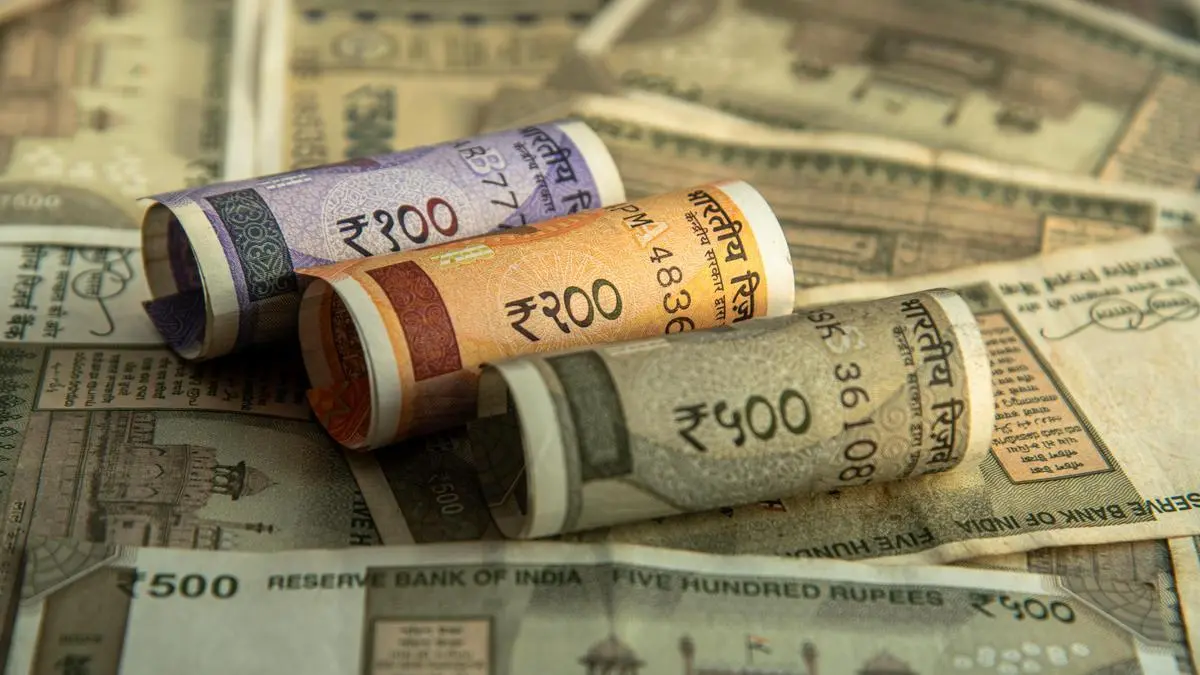
The rupee closed
modestly stronger on Friday, aided by an easing in oil prices
and the dollar after a searing rally in both kept up the
pressure on the local currency through the week, eliciting
central bank interventions to avert sharp falls.
The rupee closed at 95.8125 per dollar, up slightly
from its close at 95.9550 in the previous session. The currency
was little changed on the week.
Oil prices fell about 2% on Friday, though remained north
of $100 per barrel as investors weighed attacks against Saudi
Arabia by Houthi fighters against the possibility a truce
between the US and Iran amid ongoing diplomatic efforts.
Elevated energy prices have also lifted global bond yields
as investors wager that central banks will need to raise
borrowing costs to combat inflation.
“Markets remain reluctant to price in any optimism into oil
prices, which keeps risks on the upside for rates,” analysts at
ING said in a note.
Higher rates exert pressure on risk assets like emerging
market currencies and equities. India’s benchmark stock index
posted its longest weekly losing streak in six years on Friday.
Persistent intervention by the Reserve Bank of India have, however, contained pressure on the rupee, traders said. The central bank has also used sell-buy swaps to mop up excess rupee liquidity from the banking system.
The swaps, alongside relatively lower liquidity in the
forward market and the cutting of stale received positions,
pushed dollar-rupee forward premiums up sharply this week, a
swap trader at a bank said.
The 1-year forward yield rose as much as 28 basis points in
three sessions to touch 3.50% on Friday, its highest level since
May.
“Typically, such sharp moves cool off after market
positioning gets lighter,” another swap trader at a bank said.
“That should happen (this time too), but global risk
factors could keep positioning light for the time being,” the
trader added.
Published on September 25, 2026
