

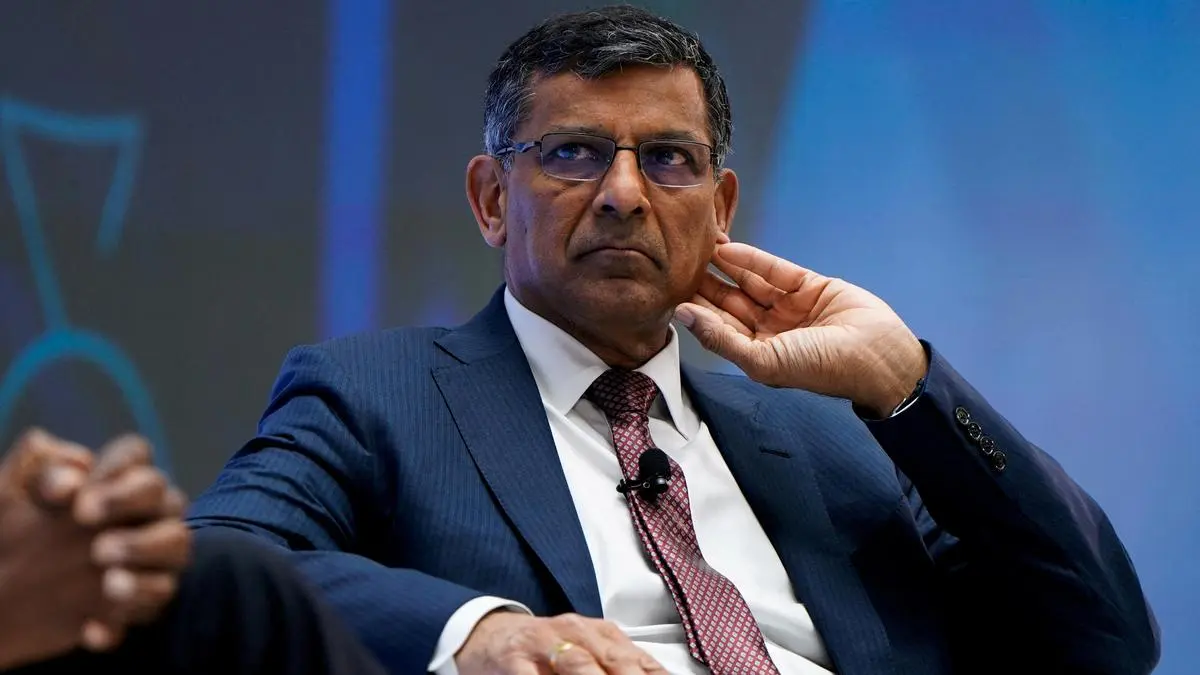
FILE PHOTO: Former Reserve Bank of India Governor Raghuram Rajan
| Photo Credit:
ELIZABETH FRANTZ
India should not “fixate on a
number” for its currency level or run down foreign exchange
reserves to defend the rupee, Raghuram Rajan, former Reserve
Bank of India governor, said in an interview with Reuters on
Tuesday.
The rupee has lost about 6 per cent of its value so far in 2026,
making it the second-worst performing currency in Asia, and hit
a record low of 96.96 in May.
“I think the first response would be, don’t panic,” Rajan
told the Reuters Global Markets Forum, warning that there was
scope for the current account deficit to widen further if oil
prices stayed elevated.
High oil prices, surging US Treasury yields and continuing
foreign equity outflows have compelled the central bank to step
up intervention to limit cascading risks to inflation and
broader financial stability.
Earlier this month, RBI Governor Sanjay Malhotra did not
rule out using monetary policy measures to stabilise the
currency.
“I would take a very sensible view and look at the longer
term, and examine whether this (situation) is an outlier
relative to past episodes,” said Rajan, now the Katherine Dusak
Miller Distinguished Service professor of finance at the
University of Chicago Booth School of Business.
“Some currency depreciation is not necessarily a bad thing
in this kind of environment. It allows you to stabilise your
exports (and) makes your goods more competitive.”
India has deployed about half of the over $140
billion secured through special measures earlier this year to
support its currency and absorb surplus banking system
liquidity.
“We just spent a lot of money trying to get the FCNR(B)
money in. It would be a shame if that was quickly spent in
defending a level, which historically we haven’t done.”
If the Middle East war reignites and Gulf energy
infrastructure is hit, oil-consuming emerging markets would
suffer, he said.
“As they say, ‘you ain’t seen nothing yet,’ if this really
gets that bad.”
Rajan took charge as the RBI chief in 2013, at the time of a
crisis when India was seen as part of the “fragile five”
economies.
Published on October 27, 2026
